Estate Planning Preparation
2 September 2026
Estate Planning Preparation
Building an estate plan or reviewing an old plan will be more productive if you consider the key parts of what you will need when meeting with an estate planning attorney.
An estate plan addresses three main areas
| BENEFICIARIES | ASSETS | CONTROL |
|---|---|---|
| Who are the people and organizations you want to provide for at your death? Do you have obligations at death such as to creditors, joint business and asset owners or ex-spouses? | What are all of your assets, location, approximate value, ownership structure and beneficiary designations? | Who should oversee making sure your wishes are carried out before and after your death? Executors, personal; representatives, or trustees to settle the estate, trustees may manage assets for decades; health care and financial agents can step in if you’re incapacitated. |
What you should think about prior to meeting with estate planning attorney
| Distribution Philosophy | Fiduciary roles | Incapacity planning |
|---|---|---|
| Will your assets be distributed outright, in stages or held longer than that? Will your assets be distributed in equal or unequal shares? Consideration to include: 1) beneficiaries’ ages and financial maturity; 2) The size of the inheritance relative to their own assets, whether the assets are liquid or complex and any exposure you want to guard against, such as divorce or creditors. Special circumstances A blended family (think of children from a prior marriage), a beneficiary with special needs, an intentionally unequal division or concerns about a beneficiary’s spending. Honestly identifying – including deciding whether you’ll explain your reasoning to the family – is often the difference between a plan that works and one that surprises. Geographic locations Are you or any of your intended beneficiaries or fiduciaries non-U.S. citizens or living outside of the U.S.? Do you have assets located outside of the U.S.? These factors may require additional planning or a specialist, and it’s important to flag them early. | Who serves as executor, trustee and guardian? Identify who back each of them up. The best choices are not automatically the oldest child or the closest friend. Instead, they are people who are organized, impartial and genuinely willing. It’s worth considering whether a professional belongs in the mix: professionals bring neutrality and permanence and also keep trust decisions from complicating family gatherings. Business and illiquid assets Should a business interest or real estate holding be sold, retained, or passed to a specific heir? If one child gets the company, do the others receive equivalent value? Will the estate have enough liquidity to cover taxes without a forced sale? | Who makes financial decisions and medical decisions if you’re ever unable to? There may be different people based on different strengths A financial agent needs diligence and comfort with detail; a healthcare agent needs emotional steadiness to carry out your wishes under pressure. Charitable intentions Decide whether philanthropy plays a role in your plan and in what form – during life or death, via a simple bequest or a vehicle such as a foundation. Ig giving matters to you, consider whether you like your children to carry it on. |
Your first or review meeting is for discovery. You do not need complete and precise information.
| Personal & Family | Financial Snapshot | Existing Documents |
|---|---|---|
| Full legal names, dates od birth, and contact information for your spouse, partner, and children. | A general list of assets and approximate values; real estate, investment and retirement accounts, business interests, life insurance, significant personal property. | Any current will, trust or powers of attorney – even outdate4d ones provide useful context |
| Names and contact information for those you’re considering as executor, trustee, guardian, health care proxy, or financial power of attorney. | How major assets are title – individually, jointly or in trust | Business agreements with succession or buysell provisions, if applicable. |
| Current beneficiaries or retirement accounts and life insurance policies | ||
| Significant liabilities, such as mortgage or loans. | ||
| State of residency and any past of future moves between states. |
Setting expectations at first or review attorney meeting.
| Discovery, not decisions The first meeting is mainly for your estate attorney to learn your full picture – family assets, goals, etc. Don’t worry about having every answer. | Direct inquiries about your situation Expect direct questions about your wealth, family dynamics, and sensitivities. These questions are confidential, provided the conversation is between you and your attorney and necessary to give you proper advice. | Trust draft and not a final version You will likely leave with a proposed structure and next steps, not finished documents. Plans are typically refined over several meetings. |
This material does not constitute legal, tax, or financial advice. We advise you to consult with your legal and tax advisors before finalizing your estate plan.
SHARE
Many assume that a happy retirement comes down to building enough wealth over a lifetime of work that will ensure comfort in their later years.
In simple terms, will the financial assets accumulated generate the monthly income necessary to sustain their retirement lifestyle? If they can check that box, well, they ar
First let it be said that for the number of people served (73 million) and the amount of money paid out annually ($1.5 trillion), the Social Security Administration does an admirable job of keeping everything straight. More than 99% of beneficiaries receive their benefits on time and in the correct amount and never nee
Retirement as a formal idea and lifestyle is a relatively modern concept. For most of human history, people worked until they were physically unable and then relied on family or community support.
It wasn’t until the industrial age that the concept of retirement was born.
In 1875, the American Express Company esta
Executive summary: Adults ages 25–40 are being targeted by fast-growing digital scams—especially fake job offers, student loan forgiveness cons, and payment app fraud. This briefing outlines what’s changing, the red flags to watch for, and the practical verification steps we use with clients to prevent losses before mo
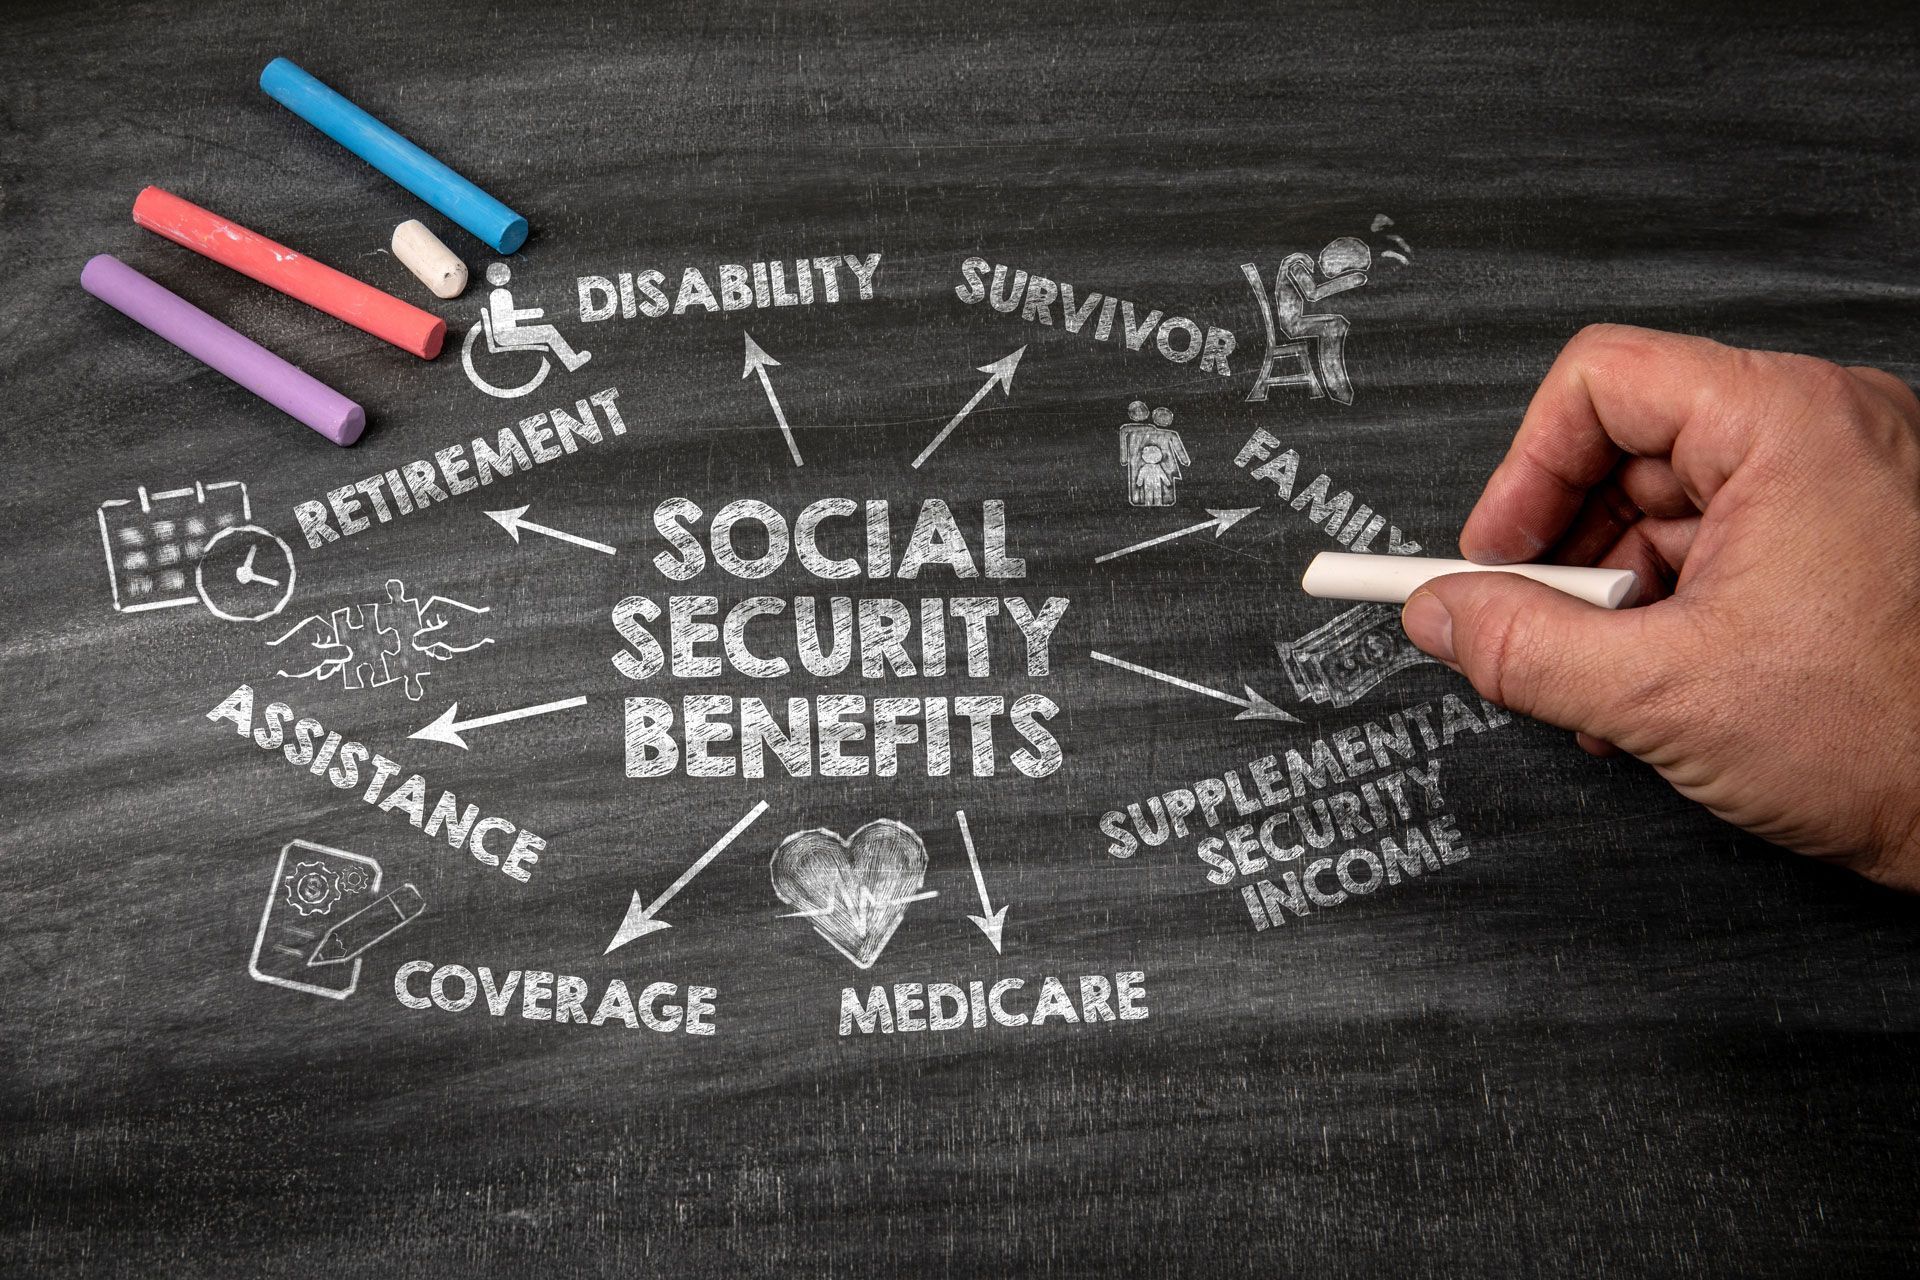
We recognize the complexities involved, and our goal this month was to provide you with an overview. But we can help you explore various options based on your circumstances. While the final decision rests with you, we’re happy to support you and address any questions along the way.